Stock counting and variance management: same day, not at the count
A stock variance is when the quantity in the ERP does not match the physical quantity on the shelf. If it is found at the year-end count, finding the cause is very hard, because months have passed. When continuous counting, barcode and lot tracking are used together, the variance is seen the same day, a likely cause is sought, and the correction goes into the records with a person's approval.
What is the difference between periodic and continuous counting?
In a periodic count the warehouse stops on a set date, everyone counts, and the variances are recorded. It is usually done once or a few times a year. In a continuous (cycle) count, a small section is counted every day while the warehouse keeps working; over the year the whole stock is covered several times.
- Periodic count: the warehouse closes, work stops, variances are found in bulk and the cause is often unknown.
- Continuous count: work does not stop, the variance is small and new, so its cause is remembered.
A periodic count may be needed for legal or financial reasons; do not give it up. But continuous counting makes sure the variances are already known and explained by the time you reach the periodic count. That way the periodic count becomes a verification, not a discovery.
How is continuous counting planned?
You do not need to count all products at the same frequency. Split the count list by product value and movement speed.
- High-value or fast-moving products are counted more often.
- Low-value, slow-moving ones are counted less often.
- Stock cards that fall to zero or go negative go onto the count list immediately.
- A product with a variance is counted again the next day.
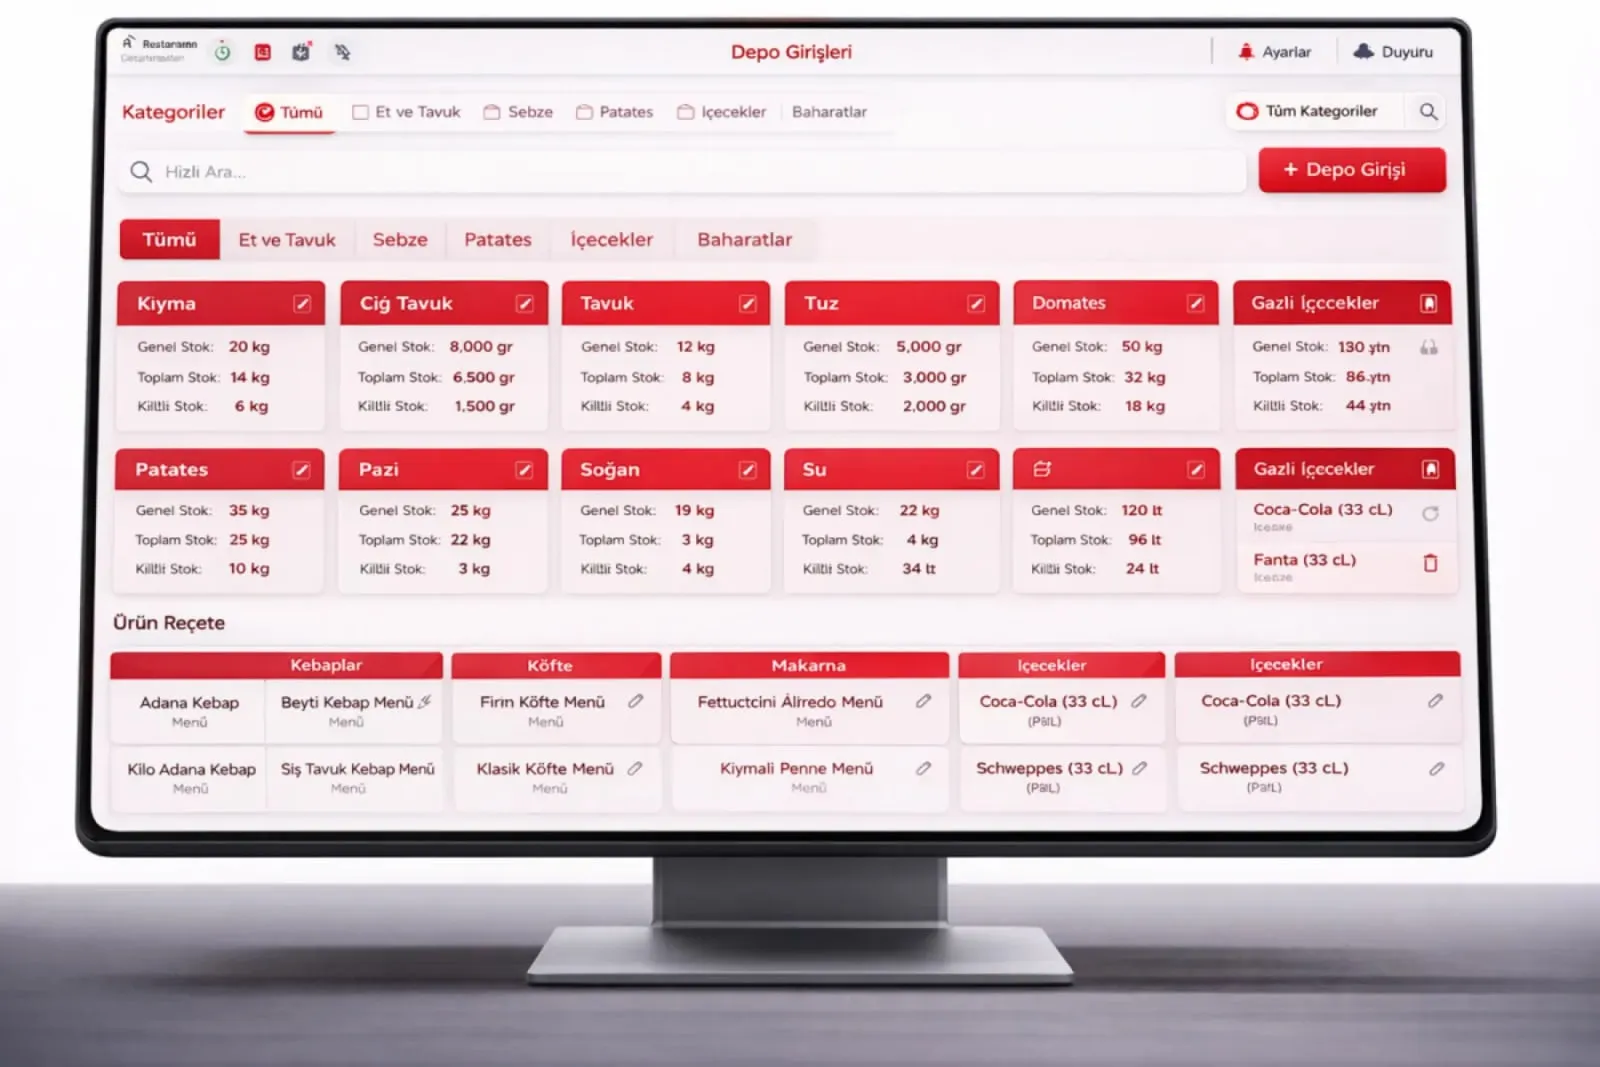
Have the ERP generate the daily list; the person counting should see only the shelf and the product on screen, not the quantity in the system. A person who counts while seeing the quantity unconsciously drifts toward that number. A blind count catches variance more accurately.
Even in a small warehouse, dividing the count into sections makes the job easier. Split the count list by aisle or shelf group, give each section to one person and ask them to confirm when they finish counting. That way, when a variance appears, it is clear in which section and in whose count it appeared.
How do barcode and lot tracking change counting?
With a paper list, two errors are common: marking the wrong product and later entering the count wrongly in the ERP. A barcode reader or handheld terminal removes both, because a scanned product is matched to the record instantly.
For products with lot or serial tracking, counting should be done by lot. The total quantity may be right while lots are mixed up; for products with an expiry date this means direct loss. If the lot information is in the barcode, no extra work is needed during counting.
- Give every shelf and location its own barcode; scan the shelf before scanning the product.
- Counted quantity should go to the ERP instantly, with no intermediate paper.
- Keep a manual entry route open for a product whose barcode will not scan, but flag it in the record.
What usually causes stock variances?
A variance is most often not theft or loss; it is small carelessness in the process. Looking at causes in groups lets you group the solutions too.
- Receipt error: quantity or unit entered wrongly at goods receipt (pieces instead of cartons).
- Issue error: shipped but the waybill was not issued, or was issued with a different product.
- Wrong shelf or location: the product exists but sits somewhere else.
- Similar-product mix-up: two colours or two sizes picked in place of each other.
- Returns and rejects: returned goods were not booked into stock.
- Scrap and spoilage: thrown away without being recorded.
- Real loss: theft or damage. It is the part left after the other causes are ruled out.
Here an AI agent helps. When the agent finds a variance, it looks at the recent movements in the ERP: the latest receipts of the same product, open waybills, pending returns. It writes a likely cause and shows the related document. A person confirms the cause.
If movement continues in the warehouse during counting, note the movements at count time for the shelf being counted. If a shipment went out during the count, the variance may be a timing difference, not a counting error. To prevent this in continuous counting, the shelf being counted can be briefly set aside from movement until the count ends.
How is a correction entry approved?
Changing the stock quantity based on the count result is a transaction with a financial effect. So the person who did the count should not record the correction alone.
- Let the count variance turn automatically into a correction draft, but not be posted.
- The draft should show the product, lot, quantity variance, likely cause and related document.
- Let the warehouse manager approve variances below a certain amount and a manager those above. Your company sets the threshold.
- The approved correction should be posted with the count date and the approver's name.
- A repeating variance cause (for example always on the same shelf) should also be handled separately as a root cause.
Where do you look first when a variance appears?
When a variance appears in a count, do not correct the stock right away. Look first at the records themselves; most variances are explained there. The order below is the one that gives results fastest.
- The receipt and issue movements of the same product over the last few days.
- Waybills not yet issued or cancelled.
- Pending return and reject records.
- The quantity of the same product showing in another location or another warehouse.
- Counts of similar products (colour, size, packaging): if one is short, the other may be over.
If none of these explains it, count the product again the next day. If the second count gives the same result, send the correction draft for approval. A recount is cheap; a wrong correction comes back in later months as a new variance.
What should be tracked in the variance report?
Making the correction is not enough; the trail of the variance must be kept. A small monthly variance report shows which shelf, which way of working or which supplier is causing problems.
- Number of variances by product and location: is it always the same shelf?
- Distribution by cause group: receipt error, issue error, loss?
- Time between the correction entry and approval: how many days does a variance stay open?
- Repeating root cause and the measure taken.
How is same-day variance detection set up?
The flow is simple: the ERP generates the morning count list, the warehouse counts by barcode, the system calculates the variance, the agent suggests a likely cause, the person responsible approves. By the end of the day the variance is either explained or flagged for a recount.
A process-time example: if two people spend three days on the year-end count and then five business days looking for variances, that is 8 days x 2 people = 16 person-days spent on counting and investigation. In a daily flow there is a small job every day. The total effort may not change much; what changes is when the variance is seen.
To start, try one warehouse and the few hundred most active products. Record variance causes in the first month; once you see which cause group dominates, fix that one first.